
Truly great businesses come in all shapes and sizes. While different industries have their own set of rules, distinct players, business models and, of course, customer needs; those that dominate their markets always leave behind clues.
Our search for these world beaters is one which may be filled with ups and downs. Nonetheless, here are 5 checkpoints I use to ensure we can have the patience to endure the bumps on our long term investing journey at Rask.
1. Good financial foundations
Being a self-confessed numbers guy and someone obsessively curious about how things work, one of my first research stops is the annual report. While these 200 page monster pdf files can be daunting, they are a critical financial health check. Similar to blood tests and x-ray scans, time spent here by investors can swiftly reveal if things are as rosy on the inside, as they look on the outside.
Checkpoint one will see me diving straight into the unit economics of a business. By sizing things up financially, we can consider how a business actually makes money and what margins look like. Peeling away revenue segments shows us what products and services drive the bulk of sales and the existence of any growth engines.
Equally important is how a company spends its cash. Similar to scrolling your finger down at your own bank statements, you’ll be surprised to see what costs a company has racked up, and also what direction margins are trending. Only after accounting for all the cash coming in, less everything going out the door, can investors really appreciate the profit generating potential (or lack thereof) for us as future owners. Sounds basic, but these steps build our understanding of the business and let us ultimately compare different companies and competitors on an apples to apples basis. At the end of the day, it is free cash flow which is pivotal for any investor to properly assess.
Part two of the annual report is a structural test. Casting a keen eye on the financial position using its most recent balance sheet. Here we’re on the lookout for the type of assets it’s holding, as well any obligations and liabilities it’s on the hook for. One key health check is net cash: weighing up the short and long term debt vs cash in the company coffers. While simple, it can quickly separate strong self-funding businesses, against those who come to shareholders hat in hand, either burning cash unsustainably, or riddled with debt and poor business models.
A metric that encapsulates the importance of net cash is enterprise value. While many investors often use market capitalisation to determine a company’s size, there are a few reasons why enterprise value holds an edge.
Take two identical Toyota Corolla’s (same colour, make, specs and condition) both listed for sale at $20,000. Corolla #1 is under finance and still owes $5,000, while Corolla #2 has a $2,000 wad of cash sitting in its glove box for its new owner. Market capitalisation is the equivalent of only looking at the sticker price for a car (current share price x total number of shares). With enterprise value, investors can elevate themselves to level 2 thinking. Where Corolla 1’s true cost is $25,000 ($20,000 price + $5,000 loan to pay off), Corolla 2 is just $18,000 ($20,000 – $2,000 of cash which you can put in the bank).
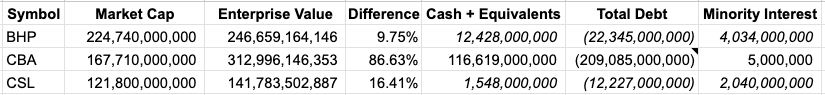
*Calculated on 3 October 2023, BHP & CSL cash, debt and minority interests are stated in $USD
As you can see from the table above, market value dismisses the capital structure of a business. While enterprise value rewards those hoarding important cash piles, and punishes those with debt and more complex ownership structures.
Additional financial foundation health checks:
- Check for red flags in the form of strange items in the financials, one-off expenses that dramatically affect profitability, as well as complex ownership structures or subsidiaries that muddy the waters. Try the Accounting Notes at the back.
- Scan the Cash Flow Statement to identify, reverse and undo any accounting trickery that distorts true cash earnings.
- Lookout for high amounts or Goodwill that favour acquired over organic growth, or mounting carry forward losses. A history of capital destruction doesn’t bode well for a bright future.
- Don’t be afraid to chuck something in the too hard basket. Simplicity is often a good sign, and saying no can often avoid headaches down the road.
2. The special sauce
Businesses disrupting incumbents, or those already at the top of the food chain, often have a certain x-factor about them. Call it uniqueness or special sauce, it’s that something which all market leaders have, and what the chasing pack are trying desperately to recreate.
This uniqueness comes in different styles too. On the product side it can be technology and patents like industry leading radiology software from Pro Medicus, or brand power that compel consumers to happily pay Louis Vuitton’s luxury tax or Nike’s premium pricing. Other forms may also include intellectual property held by CSL, who possess a world-class portfolio of therapies, plasma collection and developing vaccines that people trust.
Company culture can also manifest as an advantage too. Becoming a desirable workplace has big long term advantages, making them a magnet for attracting and hoarding talent.
Google infamously has a hiring process even more selective and competitive than Harvard or MIT, a 0.2% acceptance rate from 3 million applications every year. Think about the collective brain power housed in such a purpose built environment with motivated individuals. Support this with deep resources and market leading pay (that it funds from its amazing business model) and it’s no wonder Google HQ has been an innovation powerhouse.
Finding and identifying this magic often leads investors to a company’s most important asset: its competitive edge and economic moat. Durable moats tend to be inextricably linked to this secret sauce, and help businesses gobble up market share and shield profits from competitors.
3. Customer love
“If you like the store, chances are you in love the stock”
Peter Lynch, 1977-1990 manager of the Magellan Fund at Fidelity where he averaged a 29.2% annual return.
When businesses have products that customers simply love, there is almost inevitably enormous value creation. After all, customers who willingly and repeatedly hand over their hard earned, can build to form immense long term loyalty.
Key to this love is establishing and growing brand equity. It fuels habits like repeat purchasing and can unlock additional growth opportunities to sell new products into. King here, and by no coincidence the most valuable company on the planet right now, is tech giant Apple.
Not only do most iPhone owners upgrade every couple years like clockwork (recurring revenue ✓), but think about all the other Apple products that somehow make their way into your household. From Airpods that let you listen to your favourite podcast (thanks, Australian Investors & Australian Finance Podcast listeners), to an Apple watch to track your health and fitness, or a Macbook as your new computer. Executed well, strong brand equity can turbocharge sales through even higher margin products like iCloud storage and App store purchases – giving companies multiple ways to win big at scale.
Customer love also leads to benefits on the cost side too. Whether you are a fanboy or fangirl, or have succumbed to the social pressure of the blue iMessage bubble, there’s a high chance you’ve experienced this very positive word of mouth effect. Making products that famously “just work”, or having warranty and replacement programs result in happy customers for the long haul, building increasing trust along the way. This trust can slash marketing and new customer acquisition costs too, while also supporting high renewal rates locking in predictable future revenue streams.
Importantly, investors should not mistake high switching costs for customer loyalty. In this age of information abundance and public reviews, there’s no place to hide for companies who intentionally lock in customers against their will, or those just facilitating a commoditized function, rather by their own wants and desires.
The Covid-19 pandemic aside, globalisation and modern supply chains mean that producing goods for today’s consumer is the easy side of the equation. Businesses that seek to conquer customer demand can forge pricing power and avoid margin erosion and brand destroying discounting cycles. How else can you explain why in 2023 customers will line up for the latest iPhone 15, or why even used iPhones can sell for more than newer Android counterparts with better technical specs.
This FOMO and very intentional market position basically boils down to customer love. Masters of it often command a cult-like following and show stark differences in pricing, demand, and ultimately profits and cash flows. Just look at Bunnings, Australia’s undisputed default choice for home improvements, or how Kmart is the only destination for discount homewares.
Great businesses also understand the right balance when leveraging this love. Not flexing this pricing power to take advantage, but understanding exactly how their products drive long term value and repeat purchasing. It’s not just about today’s sale, but also the next.
4. Network effects
One of the most powerful traits a company can possess is the ability to harness network effects. When these networks and marketplaces gain dominance, they become extremely difficult to dislodge, resulting often in natural monopolies.
As each new user is added, the network’s strength is enhanced by increasing liquidity from both supply and demand sides. Every new node brings with it another connection, and scale can be attained quickly as adoption snowballs with low to zero marginal costs. For www.realestate.com.au, www.carsales.com.au, or www.airbnb.com this means you’re either first, or a very very distant second.
Key to this exponential growth is top dog status. As the numero uno, its death by 1,000 cuts as the gap widens with every user. Profits are then reinvested at incrementally higher and faster clips, strengthening the platform and increasing an already clear lead. Competitors meanwhile, struggle with inferior products. Finding themselves unable to attract new customers, even by slashing fees or by dangling juicy joining incentives. This power dynamic means buyers will always seek out the best prices and selection from the most sellers, while sellers naturally flock to the most demand and buyers.
Put simply, these businesses can employ large amounts of incremental capital at very high rates of return, and importantly over far longer periods than most investors realise. It’s really a special ability to reinvest cash made from the business back into itself at great returns, again and again, year after year.
5. Shareholder friendly management
“Show me the incentives, and I’ll show you the outcome”
Charlie Munger
While it’s true uncles Warren and Charlie both prefer great businesses over great managers, one surefire way to capital destruction is poor leadership. It’s why so many investors seek out founder-led businesses.
More often than not, these founders and managers show real care for their business, and have earned trust with long track records of execution. While skin in the game can align interests, look for a management team whose reputation and personal wealth are truly tied to the business. These are the few who will consistently do the right thing by shareholders. It’s at this intersection where fates are tied and culture can mean much more than words on the values page of a company’s website or any monetary incentive.
With the material rise of performance based bonuses, it’s also critical for investors to understand exactly how incentives are being awarded. By diving deep into remuneration details, we can understand if performance targets align with our objectives. Are they creating true long term value for all shareholders, or simply lining their own pockets?
It’s sadly all too easy for businesses to artificially inflate top line sales, either through bolt on acquisitions or feeding marketing machines with eroding economics. Without a sharp eye on unit economics and profit margins, uninformed shareholders may also find themselves funding CEO yachts, instead of rivers of free cash flow.
Likewise, long term investors should keep an eye on non-cash incentives. These are silent killers that dilute existing owners, where excessively generous equity and options packages have become all too common for high growth tech companies to attract engineers and talent.
I think the very best leadership and management teams treat company funds like their own, steering the ship towards a common goal. Investors can simply track and identify management forecasts with their actual execution.
Some closing thoughts
Working without the right tools makes it doubly difficult for investors to properly assess and compare true business quality.
While these checkpoints are by no means exhaustive, or simply the only elements when researching or studying great companies, use them as a starting guide to narrow your focus and resist the temptation to stray away from the long term path.
Without such checkpoints, investors may be flying blind. Spotting these key traits early not only increase our chances of success, but can ensure our north star is always compounding in the right direction.
~~~
Agree, disagree, love it, hate it? Let me know over in the Rask Core community.