
Amazon released its Q4-2023 results last Friday, with a record-breaking Holiday shopping season resulting in the best-ever quarter in company history.
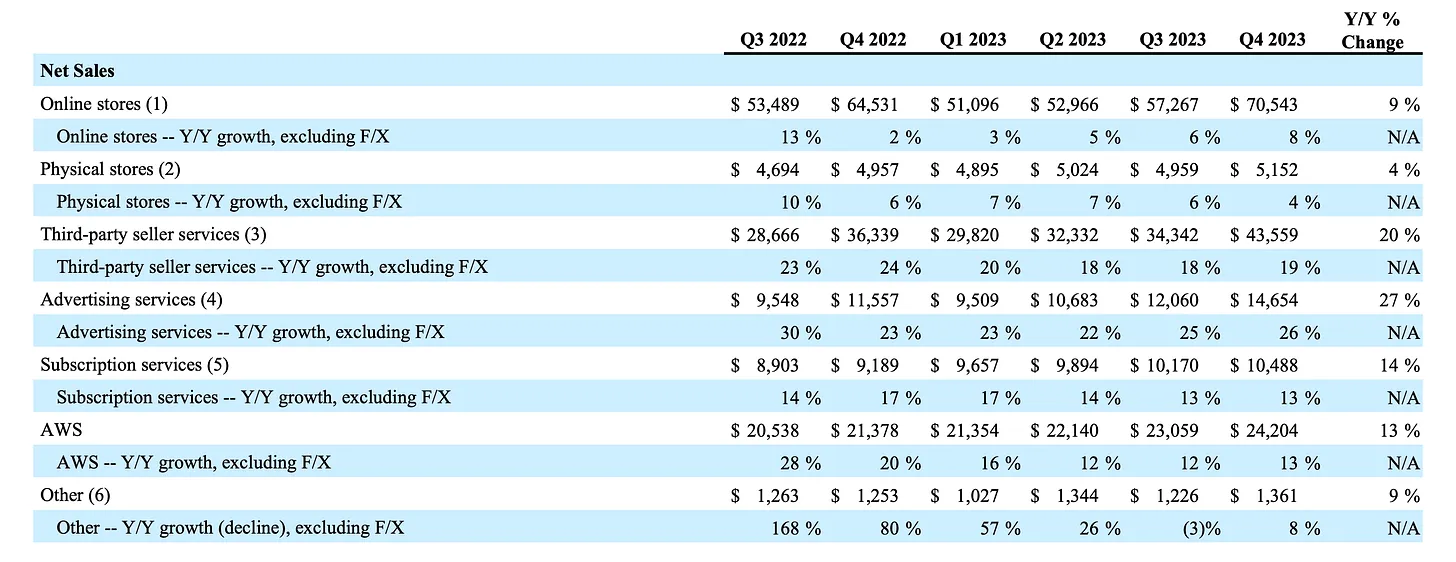
- Revenue +14%, to $170bn in Q4-2023 vs $149.2bn in 2022
- Operating cashflow +82%, to $84.9bn for the TTM, compared with $46.8bn
- Online stores +9% to $70.5bn
- Third party seller services +20% to $43.6bn
- Advertising +27% to $14.7bn
- AWS +13% to $24.2bn
Across all major high margin segments that matter: 3PL, advertising, Prime subscriptions, and AWS shrugged off recession fears and delivered some big numbers. Particularly when you look at the scale at which these business lines are already at.
While many investors claim that AWS is the only thing that matters. However, they are missing the forest from the trees. Yes, AWS pulled in an impressive $7.17bn in operating income, but the rest of the company is now really starting to purr, pushing out another $6bn.
After a tough few years with the pandemic leading to over-investment and over-building, Amazon can no longer hide the cash flow power brewing under its hood. Customers during Black Friday, Cyber Monday and the holidays purchased more than 1 billion items on Amazon, with 500 million items from small and medium-sized independent sellers and businesses.
While the business is still striving for even faster delivery times and lowering its cost to serve (delivery costs surged up +11%), coupled with AI and growing capex commitments for AWS, the future is looking bright.
3 things to watch
Here are three things I’m watching right now:
- Launch of advertising on Prime Video. This follows Netflix and others doing the same.
- Traction for Prime members latest health care add on. For $9 per month (or $99 annually) US prime members can get One Medical, to access high-quality primary care. For those unfamiliar, it’s Amazon’s big move to disrupt the medical industry. Powered by a mobile app that lets patients across 19 major US cities access in-person appointments, renew prescriptions, as well as remote video chat bookings. It’s another big market in the behemoth’s crosshairs.
- Continual strength in 3PL (third party logistics). For possibly the world’s largest marketplace to still produce +20% growth year over year (YoY), I think this means Amazon’s story isn’t over. Not by a long shot.
The market is missing how immensely profitable this dominant business is, as it reaps the benefits from its long-term bets. For me, it is still very much Day 1.
Disclosure: Kevin owns shares of Amazon and will continue to hold.