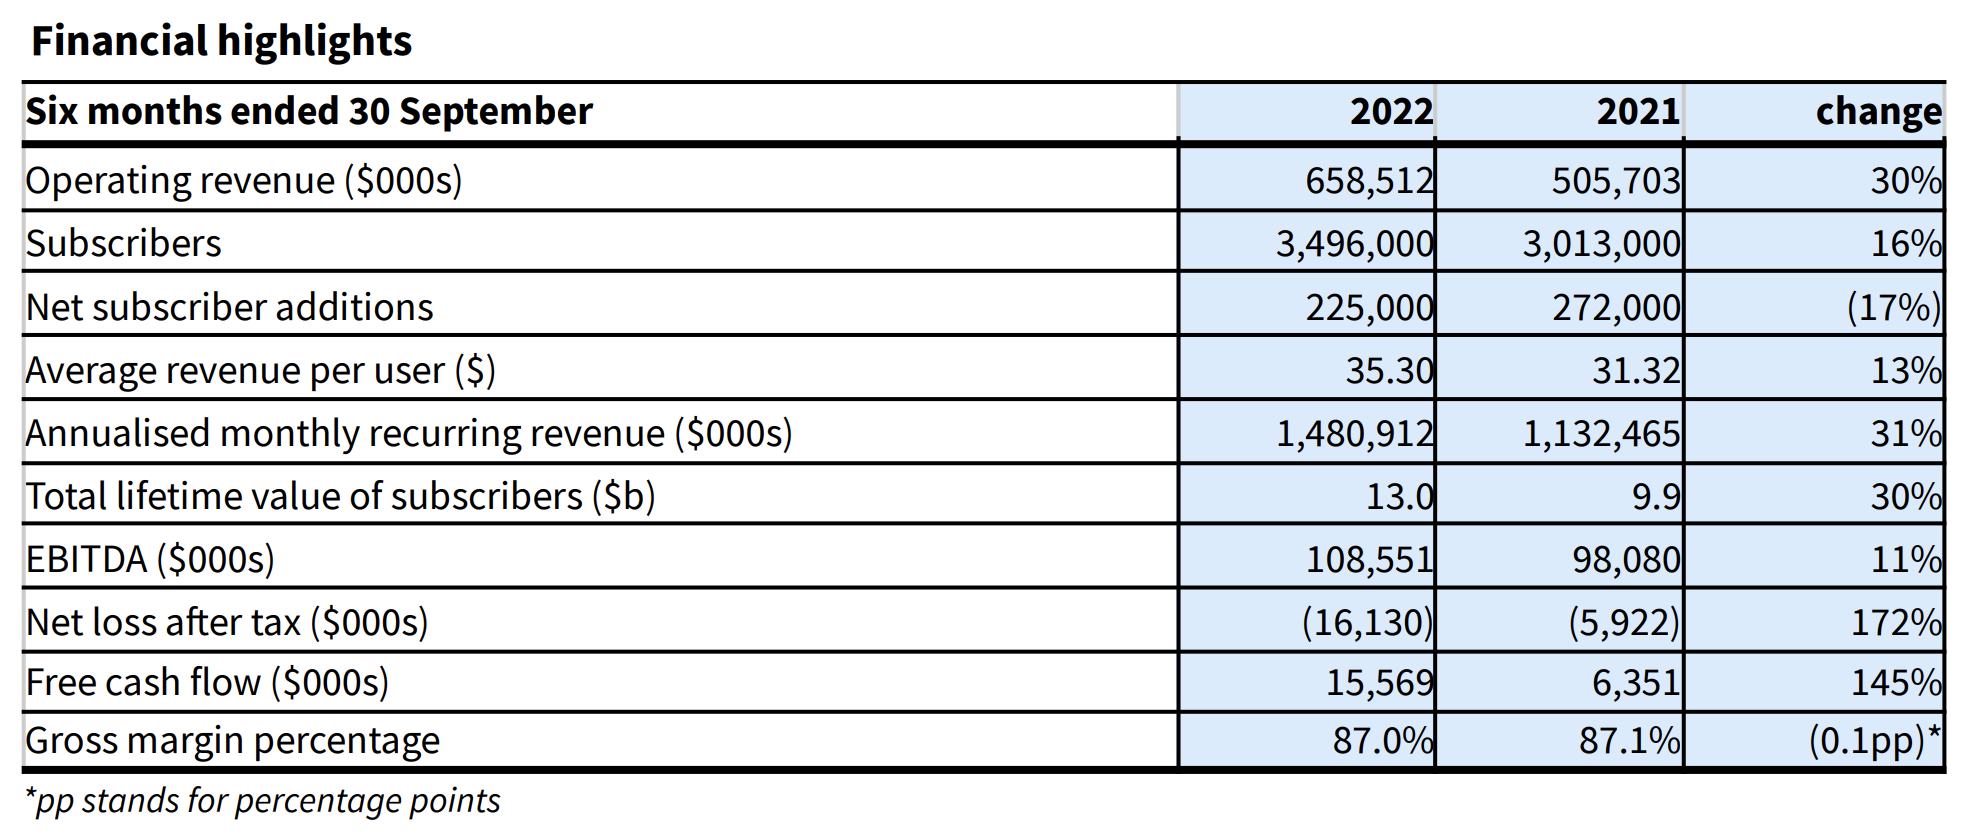
Today, Xero Ltd (ASX: XRO) released its FY23 half-year results, announcing slower (but expected) new subscribers and a weaker profit result than the market was expecting.
I own Xero shares.
About Xero
Xero is a world leader in cloud accounting software, second only to Intuit Inc (NASDAQ: INTU) (owner of Quickbooks). While Xero’s origins are in New Zealand, where founder Rod Drury was backed by the MYOB founder (a competitor) with capital and support to build an accounting solution that would be based entirely in a browser.
Xero costs ~$50-$100 per month and it is sold through expert accountants, meaning it’s sold by expert whose clients foot the bill. Xero likely saves accountants (and small-medium businesses) dozens of hours and thousands of dollars every year.
In the future, having conquered New Zealand and Australia, Xero is maybe two-thirds of the way through its UK expansion (where it competes against Intuit and Sage Group), and at the beginning of its Canadian business expansion. I believe the USA will be won by Intuit.
I think Xero is one of the highlighted quality companies on the ASX. To be sure, it could still stuff up, particularly as the CEO transitions under a Chair who I’m not convinced about, or as competition increases. But it makes a great product, in a growing market, with an army of passionate customers.
Financial highlights
Low lights
The few key weak spots for Xero are the slower-than-ideal subscriber additions in the UK, which was well flagged by management and me a few months ago; the CEO transition away from Steve Vamos, which seems to be done right; and the lack of profitability, which the company seems aware of. That said, Xero Chair David Thodey also oversees Tyro Payments (ASX: TYR), which has been a disaster for investors who have been wondering why the company does not focus on profitability. So that’s a key risk to my modelling.
Summary
I’ll be doing more research on the company’s results and CEO in time. However, my valuation range is from around the current share price, up to $75 — using conservative metrics. I’m using a 10% discount rate to get to that.
For me, this is a rare chance to buy one of the ASX’s best companies at reasonable prices. I don’t know what will happen to the Xero share price in the short term (1-2 years) but I’m confident it’ll be a much bigger business in 5 years. So I’ll likely add to my position if we see any more weakness in the stock price.
Disclosure: I own shares of Xero and will continue to hold.